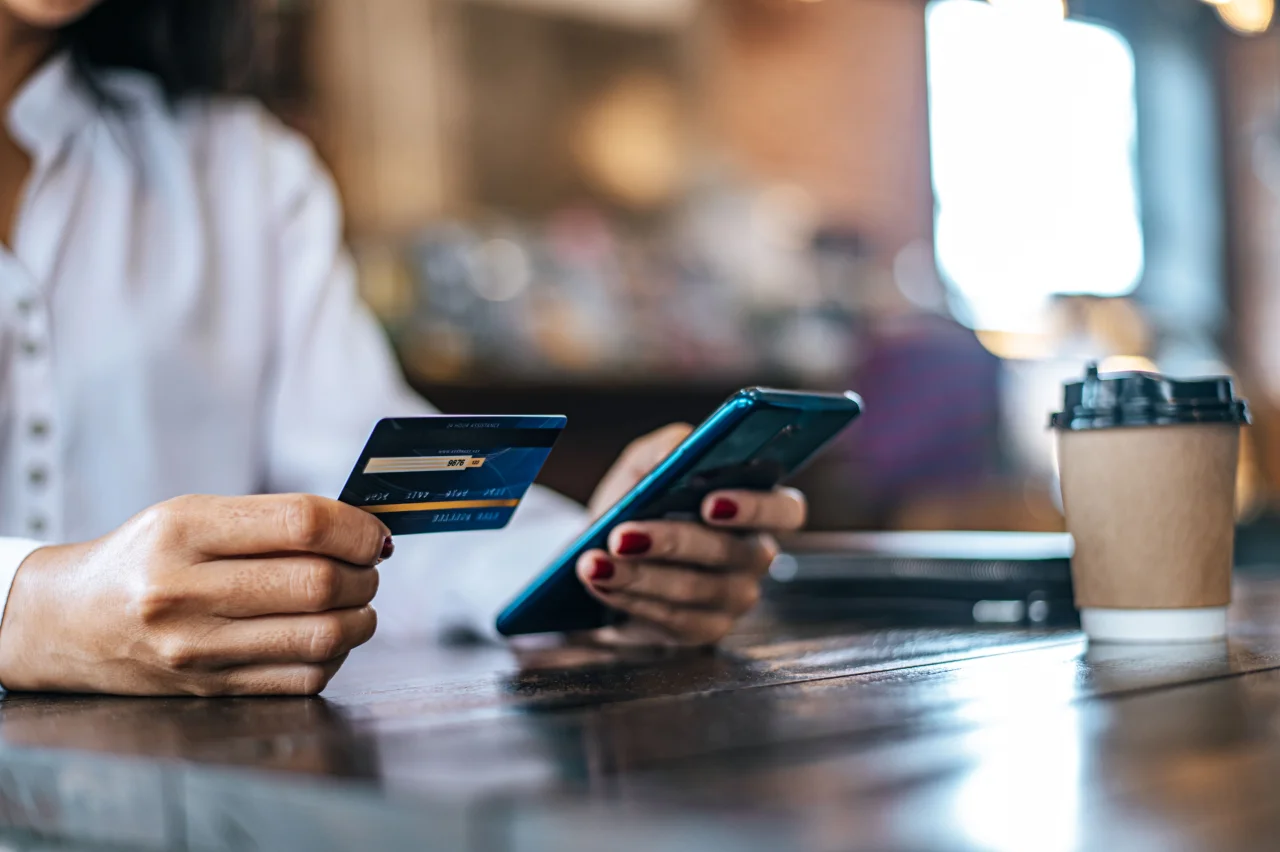
Get rewarded for everyday spending
Choose how to redeem your rewards
Keep costs low with smart use
Reward credit cards work in the same way as other credit cards. They can be used to make purchases in person or at a distance – online, over the phone or by mail order. However, reward cards allow you to earn points that can be redeemed for rewards of various kinds.
There are various different reward schemes available but most allow you to build up points depending on how much you spend on your card. These can then be redeemed for different rewards depending on your credit card and award scheme.
Most rewards cards award you points for every £1 you spend. Some schemes will, however, award more points depending on where you use your card. Cards issued by the major supermarket chains, for example, may offer more points when you spend in their stores.
Points can typically be redeemed as vouchers to spend with participating retailers, or as discounts at selected entertainment and retail outlets. Some cards also let you earn airline points or miles instead, such as Avios, which can be put towards the cost of flights.
Cashback cards are a special type of rewards card that give you a straight cash reward instead of points that can be redeemed for various rewards.
Rewards typically fall into a few main types, so it's worth knowing which suits your spending before you compare cards:
Points cards - earn points on spending, redeemable for vouchers, products or travel, like some American Express Cards.
Air miles cards - points convert into airline miles such as Avios, useful if you travel regularly.
Store and supermarket cards - earn points or vouchers with a specific retailer.
Cashback cards - earn a straight cash percentage back on spending instead of points.
Rewards cards work well if:
You clear your balance in full each month, so you earn rewards without paying interest.
The rewards you'd earn genuinely match how you spend.
Any annual fee is comfortably outweighed by the value of the rewards.
They might not be worth it if:
You tend to carry a balance from month to month - interest charges can quickly outweigh any rewards earned.
You'd find yourself spending more than usual just to chase rewards.
You're not confident you can stay within your credit limit.
Some rewards cards have comparatively higher interest rates than other credit cards. If you pay your balance in full every month this should not be too much of an issue but if you have an outstanding balance that incurs interest, the extra interest charged could outweigh the value of any rewards you earn. The value of cash back rewards are relatively simple to work out but the exact equivalent value of other types of reward can be trickier to work out.
Some rewards schemes may also be withdrawn if you fail to make at least your minimum payment for a given month. If this is the case you may lose any points that you had already built up. Even if you do not pay off your balance in full you should always ensure you make the minimum payment as this can also trigger fees and affect your credit rating. Setting up a Direct Debit to cover at least your minimum amount is a good way to make sure you never accidentally miss a payment.
The right card depends on how you spend, not just which one offers the biggest headline reward. A few things worth checking before you compare:
How you spend day-to-day - if most of your spending is at one supermarket or retailer, a store-linked card could earn more than a general points card. Frequent travellers may get more value from an air miles card instead.
How rewards are earned and redeemed - points schemes vary widely in how many points you get per £1 and what they're worth when redeemed, so compare the details rather than assuming similar cards work the same way.
Annual fees and interest rate - some rewards cards charge a fee or carry a higher rate than standard cards, so weigh this against the rewards you're realistically likely to earn.
Any introductory offers - a sign-up bonus can be a nice extra, but it shouldn't be the main reason you choose a card; check what the ongoing rewards look like once the offer ends.
Your ability to pay in full - rewards only pay off if you clear your balance each month, since interest charges will usually outweigh what you earn otherwise.
Cashback is one type of reward - a straight cash percentage back on spending instead of points or vouchers. If you know you'd rather have cash back than points, miles or vouchers, our cashback credit cards guide covers that option in more detail.
They can be, if you clear your balance in full each month and the rewards you earn genuinely suit how you spend. If you tend to carry a balance, the interest charged is likely to outweigh any rewards earned.
Some rewards cards charge comparatively higher interest rates than standard credit cards. This matters less if you pay off your balance in full each month, as you won't be charged interest at all.
No, usually not, but this depends on the specific card's terms. Rewards are typically only earned on purchases, so cash advances and balance transfers moved onto the card usually won't count towards your points or cashback - check your provider's terms to confirm.
Money Expert has been helping people compare and save since 2003. We show you credit cards from a range of UK providers, so you can compare features and apply for the card that suits you.